The Alkaimi™ model operating license is issued by Pegisai Global™ to a qualifying bank holding company. This page states what the license is, what a licensee receives, what a licensee may and may not do, who qualifies, how a licensee builds its footprint, how many licenses exist, and how to inquire.
1. What the license is.
The Alkaimi model operating license grants a bank holding company the right to operate the 100% Whole Reserve™ model in its banks, to use the Digitized Tangible Asset™ as its whole value settlement item, and to operate inside the Alkaimi walled garden network. The license is issued by Pegisai Global under an operating agreement. The licensee is independently owned and managed, and every bank the licensee operates stays under its own regulator and its own banking license.
No company in the Pegisai group, and no Alkaimi company that is not a bank holding company, engages in banking or any similar operation. The group is facilitatory in nature. Under contract to its licensees the group supports the walled garden, the ledger, and the stability and continuity of the DTA™ mechanisms. Banking is done by the licensed bank holding companies and their banks, and only by them.
2. What a licensee receives.
Access to the Mint and the due diligence team that creates the DTA. Alkaimi’s value recognition method is run there. A licensee brings a client’s asset to that process and receives DTAs for the client.
The right to use the DTA, to request the issuance of DTAs, and to earn the fees from the creation, management and operation of DTAs: recognition, custody, settlement, transmutation at the desk, and the administration of rent agreements.
Access to the walled garden network and to every bank connected to that network. The connection does what SWIFT does, in that every connected bank can settle with every other bank, and the connection does what SWIFT cannot: the network carries the value itself, not a message about a payment to be made later, and the settlement is final when the DTA moves.
Access to the Alkaimi asset reserve: the creation process, and the reserve of viable assets estimated at $4 quadrillion from which recognized value is drawn.
Access to the group’s managed gold reserve and supply line, for capitalization at entry and later, extending to other metals and minerals, monetary and otherwise.
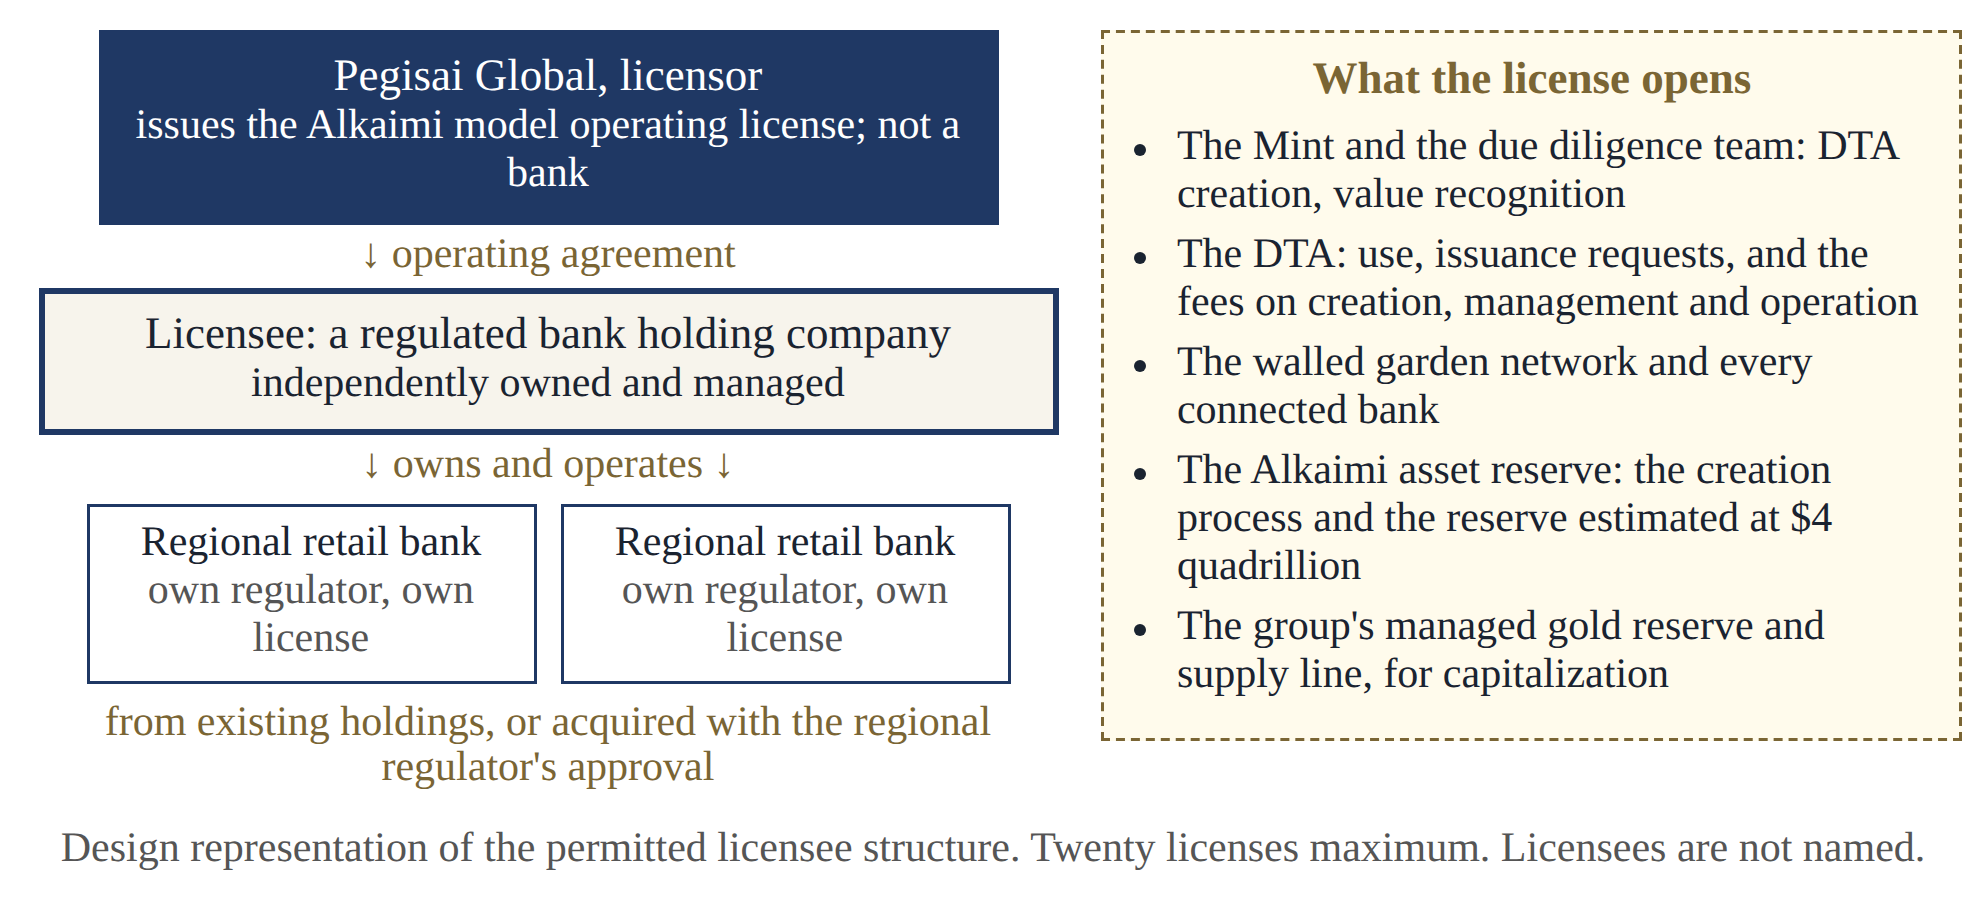
Figure 1. The permitted licensee structure: Pegisai Global as licensor; the licensee bank holding company; its regional retail banks, each under its own regulator; and what the license opens. Design representation.
3. What a licensee may do, and what the license bars.
A licensee recognizes assets, holds DTAs in custody, settles DTAs, transmutes at its desk in both directions, and administers rent agreements. Under a rent agreement a licensee may take a client’s DTA into its custodial rental account for a term, pledge that account as Level 1 HQLA, and fund a product reserve on the currency side of its desk. Any licensee may make a broad offer of rent opportunities to any party on the ledger.
The license bars a licensee from placing a lien on a client’s DTA, pledging a client’s DTA for the licensee’s own account, or creating any claim against a client’s DTA. A licensee holds custody, not title. The operating agreement states the full terms, and a breach suspends the license.
4. Who qualifies.
A regulated bank holding company with a governance record that meets the entry standard, and a capital position at or above the model’s minimum, or the capacity to reach that minimum through the managed gold reserve. Qualification is assessed at application, and the capital requirement is set for each licensee in its license offer. Licensees are not named by the group.
5. Building the footprint.
A licensee operates the model through regional retail banks, from holdings the licensee already has or through acquisition. Each acquisition is approved by the regulator or central bank of the region in which the bank sits; that approval attaches to the bank license changing hands, not to the Alkaimi model. The managed gold reserve is available to a licensee for the capitalization that entry and expansion require.
6. Twenty licenses.
The Alkaimi model is licensed to a maximum of twenty bank holding companies. The first four licenses were issued in 2023, the four licensees completed network testing that year, and those licensees entered wholesale settlement on 1 September 2026.
7. The phase, and how to inquire.
Operations are currently restricted to wholesale settlement, with consumer retail operations targeted for 2028. Licensing and business inquiries are received in writing at inquiry@pegisai.global.
The Pegisai group does not take unsolicited proposals by telephone. An intermediary must identify the principal he represents in the first message; the group does not engage intermediaries and pays no fee on any unsolicited introduction.
Inquiry form fields: institution, legal name and jurisdiction; primary regulator; bank holding company with retail bank holdings, yes or no; message.
This page contains some forward-looking statements. Read Pegisai’s statement on forward-looking statements.